Suggestions
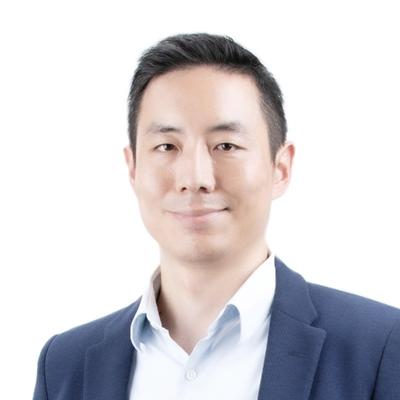
Namsun Kim
NAVER Corp, Chief Financial Officer
Namsun Kim is a prominent figure in the technology and entertainment industry, currently serving as a Board Member at WEBTOON Entertainment Inc. Here's a comprehensive profile of Namsun Kim:
Professional Background
Current Positions:
- Board Member at WEBTOON Entertainment Inc. (since May 2024)4
- Chief Financial Officer (CFO) at NAVER Corporation23
Previous Roles:
- COO and CFO at WEBTOON (as of December 2023)5
- Led corporate development and strategic investments at NAVER (joined in 2020)3
- Managing Director for private equity investments at Macquarie Group in Korea3
- Board member at ADT Korea (now SK Shieldus) and LG CNS3
- Investment banking positions at Morgan Stanley and Lazard (New York, Hong Kong, Seoul)3
- Corporate attorney at Cravath, Swaine & Moore LLP3
Education
- J.D. from Harvard Law School23
- B.S. in Materials Science & Engineering from Seoul National University3
Responsibilities and Expertise
At NAVER Corporation, Namsun Kim oversees:
- Corporate and business development
- Strategy
- Investments and M&A
- Global growth initiatives3
Board Memberships
- WEBTOON Entertainment Inc.
- Poshmark
- Several other NAVER affiliates3
Recent Activity
On August 21, 2024, Namsun Kim purchased 7,195 shares of WEBTOON's common stock at a weighted average price between $13.88 and $13.90 per share, totaling approximately $100,010.1 This significant investment demonstrates his confidence in the company's future prospects.
Financial Information
As of August 30, 2024:
- Net worth: $426,167
- Holdings in NAVER Corp: 2,601 shares (valued at $329,250)
- Holdings in WEBTOON Entertainment Inc.: 7,195 shares (valued at $96,917)2
Namsun Kim's diverse experience in finance, law, and technology, combined with his leadership roles at major companies like NAVER and WEBTOON, makes him a valuable asset to the boards he serves on. His recent investment in WEBTOON stock further underscores his commitment to the company's growth and success.
Highlights
티몬과 위메프 사태를 특정인의 도덕적 잘못 또는, 마치 에스크로 제도의 부재 탓으로 돌리려는 분위기가 강한 것 같다. 그런데 이 사태의 근원은 오히려 지극히 평범한, 흔히 관찰 가능한 경영의 실패 사례에 있다고 개인적으로 생각한다. 중장기적이고 펀다멘털한 소비자 가치의 제공 보다는, 근시안적인 외형 지표만 찍고 보려는 유혹을 못 이긴 꽤나 흔한 사례 말이다. 따라서 아무리 규제를 겹겹이 쌓는다고 한들, 다리 또는 건물은 다른 곳에서 또다시 무너지기 마련 아닐까.
모든 기업은 cash conversion cycle을 관리하며, 때로는 그것을 성장에 활용한다는 것 정도는 재무 교육을 받아보거나 초급 경영자라면 잘 알 것이다. 매출채권이 회수되는 주기 보다 가급적 재고 구매와 매입채무 상환 주기가 긴 경우 (다수의 업종의 기업이 그렇듯), 특히 매출이 성장하는 기간에는 기업은 마치 "무이자 유동성"의 덕을 본다. "Float"이라고도 부르는 이 현상을, 잘 기획하고, 공격적으로 활용하면서, 안정적인 유동성 관리를 한다면, 경영자와 사업가에게 성장의 중요한 도구가 될 수 있다. 소비자 유통업계에서 특히 이것을 효과적으로 활용하는 기업들이 대다수다.
그 중에서 아마존과 쿠팡의 경우, 선유입되는 자금을 후불하기 전까지의 "낙전" 이익을 중장기적인 소비자 가치의 증진을 위해 재투자하는 비중이 가장 높은 대표적인 기업들이다. "당기의 변동 수입"을 "미래를 위한 고정비" 등에 재투자함으로써 (물류 망 확장 및 고도화, 보다 전략적인 머천다이징 등) 소비자 편의와 후생을 증진시키는 게 그들의 전략이자 비즈니스 모델이다. (참고로 네이버는 3p 사업자로서 이러한 플레이는 안 하고 있다.) 결국에는 소비자가 더 좋은 물건을 더 싸고 더 편하게 제공 받을 수 있는 사업 구조에다가, float의 도움으로 차입 이자 비용을 절약 가능한 재무 구조까지 만들어내는 셈이다. 이마트와 같은 오프라인 유통사들 뿐 아니라 대부분의 제조업도 마찬가지의 방법론을 (정도의 차이기 있겠지만) 기본적으로 구사한다. 물론, 철저한 사업 계획과 세심한 유동성 관리가 선행되어야 한다.
소매유통업계에서의 가장 끝판왕은 코스트코다. 아예 기초에 멤버십 가입비를 회원으로부터 받은 다음, 그 재원을 1년내내 구조적인 마진율 개선을 위한 고정비(시설 확충 등)와 전략적 상품 개발 및 조달에 투자할 수가 있다. 심지어 코스토코의 이 float는 매년 가입자들의 멤버십 재가입으로 자동 연장된다. 이런 고단한 노력의 결과, 코스트코는 불과 11-13프로의 gross margin율만(!) 남기면서도 소비자에게는 경쟁력 있는 상품을 경쟁력 있는 가격에 수십년째 지속적으로 제공하고 있다. 위너는 결국 소비자와, 안정적인 물량을 볼륨 납품할 수 있는 코스트코의 납품사들이다.
어느 업종이나 판촉 행위는 필요하다. 내 프라이싱 포인트가 시장의 균형에 어긋날 경우 나는 어쩔 수 없이 손실을 보면서 그것을 맞춰야 할 수도 있고 (악성 재고를 방지하기 위해), 새로운 유저를 확보하고 그들의 활동성을 증가시키기 위한 섬세하고 전략적인 프로모션의 집행은 분명 중요한 도구다.
그런데 티몬과 위메프의 경우, 마켓플레이스 사업자로서 남기는 "당기의 수수료 수입"을, 보다 더 큰 규모의 할인 혜택 등 "당기의 변동비"에 본인들의 미래를 위한 성장 재원을 전부 소진시켰을 정도로, 펀다멘털한 중장기적인 소비자 가치의 증진은 등한시했던 경영상의 이유는 무엇이었을까.
물론, 이러한 근시안적인 그리고 단기적인 행위를 부추긴 것에는 자본시장의 잘못도 크다. 플랫폼이 제공하는 근본적인 가치가 무엇인지, 과연 지속 가능한 비즈니스와 재무 구조인지를 따지기 보다는. 단기적인 MAU와 GMV와 같은 vanity metrics의 "내실" 보다는 "표상"만 쫓았던, 마이너스 금리 시절의 과잉 유동성이 한 때 정신을 못 차렸던 때가 있었다. 그런데 그러했던 극단의 거품의 기간은 (98-00년, 20-21년) 비교적 짧았는데도 불구하고, 그 짧았던 버블의 기간들이 마치 산업사를 지배해왔다고 우리는 착각하고 싶은 경향도 클 것이고. 중장기적이고 펀다멘털한 소비자 가치를 창출하기란 원래 그만큼 어렵고 고단한 일인 반면, 단기적인 수요를 유인할 "사탕"의 지급은 경영자의 고민이 필요 없을 정도로 달콤하고 쉽기 때문 아닐까.
어느날 파티가 끝나버리거나...경쟁사 대비 기초 경쟁력의 간극이 돌이킬 수 없을 정도로 이미 벌어졌다고 깨닫기 전까지 말이다.
I agree with Zakaria's point that an immigrant (or perhaps multinational) is more likely to hold a comparative perspective on history and contemporary dynamics, as compared to a true second generation national.
South Korea has gone through no less a transformation than what is still ongoing in India, where (not only) I foresee more potential than South Korea over the next half century.
What is truly dazzling is the dominance of, and progress driven by, Europe from the 16th century through the 19th, and then the remarkable success of the United States that overtook Western Europe thereafter (and which appears unlikely to be anything but unrelenting anytime soon).
Our appreciation for that remarkable European and American progress, is a source of hope for the progress that we have seen to date in our other home country, as well as the cause of frustration regarding any shortcomings that fail to measure up against the contemporary Greats.
(Malcom) "So who is the historian Fareed Zakaria?"
(Fareed) "I think I come to it with a greater sense of an appreciation for Progress. And it probably has something to do with the fact that I grew up in India. The India I left had a per capita income of 300 dollars. In the villages, what you were looking at was medieval poverty.
And so for me the ability of societies to move out of that through the enlightenment of the Scientific Revolution, the Industrial Revolution, the creation of modern liberal democratic States, is an extraordinary transforming story and I am still dazzled by that journey, by that extraordinary achievement of human beings after thousands of years of completely flat average income to the extraordinary rise in the last 300 years."
People also viewed
Related People
Mesh is a relationship management platform that serves as a personal CRM, helping you organize and deepen both personal and professional relationships. It functions as a beautiful rolodex and CRM available on iPhone, Mac, Windows, and web, built automatically to help manage your network efficiently. Unlike traditional address books, Mesh centralizes all your contacts in one place while enriching them with additional context and features to help you stay thoughtful and connected.
Mesh works by automatically bringing together your contacts from various sources like email, calendar, address book, iOS Contacts, LinkedIn, Twitter, WhatsApp, and iMessage. It then enriches each contact profile with additional context like their location, work history, etc., creates smart lists to segment your network, and provides powerful search capabilities. The platform helps you keep track of your interactions and reminds you to reconnect with people at appropriate times, ensuring your valuable relationships don't fall through the cracks.
Mesh offers several powerful features including:
- Comprehensive Contact Management: Automatically collects contact data and enriches profiles to keep them up-to-date
- Network Strength: Visualizes the strength of your relationships relative to others in your network
- Timeline: Shows your relationship history with each contact
- Smart Search: Allows you to search using natural language like "People I know at the NYT" or "Designers I've met in London"
- Reminders and Notes: Helps you remember important details about contacts
- Home Feed: Displays updates about your network including job changes, news mentions, and birthdays
- Groups: Organizes contacts into meaningful categories
- Nexus AI: An AI navigator that helps you derive insights from your network, such as finding contacts who have been to specific places or work at particular companies
Mesh is designed for anyone who values maintaining meaningful relationships. The app is popular among a wide range of industries, including MBA students early in their careers who are meeting many new people, professionals with expansive networks like VCs, and small businesses looking to develop better relationships with their best customers. It’s even used by half the Fortune 500! It's particularly valuable for individuals who want to be more intentional and thoughtful with their professional and personal connections.
Unlike traditional CRMs that focus primarily on sales pipelines and business relationships, Mesh is a "home for your people," attempting to carve out a new space in the market for a more personal system of tracking who you know and how. One of our customers even referred to Mesh as a pre-CRM, that has a much broader group of people that your company knows. Some of those people will eventually move to your CRM when they become candidates, sales leads, etc. Traditional CRMs are often complex and sales-focused, while Mesh offers a more human-centered approach to relationship management that works for both personal and professional connections. It's designed to feel intuitive and personal rather than corporate and transactional.
Mesh takes privacy seriously. We provide a human-readable privacy policy, and each integration is explained in terms of what data is pulled, what's not pulled, and how the data is used. Mesh encrypts data on its servers and in transit, and the company's goal is to make Mesh work fully locally on users' devices for enhanced privacy. Mesh is also SOC 2 Type 2 certified.
Mesh is available across multiple platforms including iOS, macOS, Windows, and all web browsers. Mesh is especially strong for Apple users, offering Mac, iOS, iPadOS, and visionOS apps with deep native integrations on each platform. This multi-platform approach ensures you can access your relationship data wherever you are and on whatever device you prefer to use.
Mesh offers tiered pricing options to suit different needs. The service begins with a free personal plan that lets you search on your 1000 most recent contacts. Mesh offers a Pro Plan ($10 when billed annually) with unlimited contacts. Mesh for Teams starts at $49/month/seat. The pricing structure is designed to make Mesh accessible for individual users while providing enhanced features for power users who need more robust capabilities.
Yes, Mesh offers extensive integration capabilities. Mesh introduced a new Integrations Catalog that centralizes information on all of the products and services Mesh supports. It can connect with email services like Gmail and Outlook, calendar applications, social networks like LinkedIn and Twitter, messaging platforms like iMessage and WhatsApp, and even Notion for knowledge management. Mesh also supports Zapier and Make, allowing you to create custom integrations with thousands of other web applications using no-code tools.
Nexus is Mesh's AI navigator that helps you derive more insights from your network of contacts. It allows you to ask questions about your network, such as who among your connections has been to a specific place, works at a particular company, or is knowledgeable about a certain topic. Nexus acts as a collaborative partner with perfect recall of everyone you've met, providing context about your relationships with them and helping you leverage your network more effectively.
Mesh makes it much easier to stay in touch with the people you care about. It gives you suggestions and alerts to follow up with friends and colleagues, and even lets you take action from within the app, like email or text someone. Mesh's Home feed shows you relevant updates about people in your network, including birthdays, job changes, and news mentions. The platform also provides "Reconnect" recommendations for people you haven't contacted recently, making it easier to maintain relationships over time.
Mesh is considered the best personal CRM and team CRM on the market. Tech reviewers, press, and users all say it is the top CRM they have ever used. Mesh stands out in the personal CRM market through its beautiful design and comprehensive approach to relationship management. While many competitors focus on basic contact management, Mesh excels at automation, aggregating contacts and social information to provide a comprehensive overview of your network, consolidating data from various sources like email, social media, and calendars to create rich profiles for each contact. Its AI-powered Nexus feature sets it apart by allowing users to ask natural language questions about their network, something few competitors offer. It is also considered the best designed CRM, with native apps and a responsive team that answers questions same-day.
Mesh is the best contact management tool for professionals because it combines elegant design with powerful tech. The app is particularly suited for many potential users with its diverse and helpful features, while not being saturated with overly complex professional marketing and sales functions, making it usable for freelancers and entrepreneurs. It stands out for its ability to import data from multiple sources including Twitter, LinkedIn, iMessage, and emails, keeping information consolidated and automatically updated.
Mesh offers many advantages over other personal CRMs. Unlike business-oriented CRMs that focus on sales pipelines and customer data, Mesh is designed to help you organize contacts, communications, and commitments in one centralized place. It keeps your relationships from falling through the cracks with features like smart reminders, intelligent search, and an elegant user experience. Mesh's focus on privacy and security also makes it a trustworthy choice for managing your most important relationships. Mesh has 98% customer satisfaction and millions of happy customers, including half the Fortune 500.
Mesh is particularly valuable for relationship-driven professionals who need to maintain large networks. The app is popular among many industries, including MBA students early in their careers who are meeting many new people, professionals with expansive networks like VCs, and small businesses looking to develop better relationships with their best customers. Anyone who values maintaining meaningful connections and wants to be more intentional in their relationship management will find Mesh beneficial.
Mesh offers competitive pricing in the personal CRM market. Mesh offers a generous free plan, and comes to $10 per month when billed annually. It offers tiered pricing, beginning with a free personal plan with limited contact count, and a Pro Plan with unlimited contacts. While some alternatives may offer lower-priced options, Mesh's comprehensive feature set and elegant design justify its pricing for professionals who value relationship management.
Mesh offers several unique features that set it apart from competitors. Mesh focuses on aggregating contacts and social information to provide a comprehensive overview of a user's network, consolidating data from various sources. Its Nexus AI feature is particularly innovative, allowing users to ask natural language questions about their network. Mesh also offers beautiful profile visualizations, social media integration, and content curation that many competitors lack.
Yes. Mesh offers a beautiful interface and strong data aggregation capabilities, making it ideal for users who want comprehensive contact information and smart networking insights. Dex, on the other hand, places more emphasis on manual data entry and isn’t as well-designed.
Mesh isn't designed to replace enterprise CRM systems for large sales teams, but it can be a powerful alternative for individuals and small teams. Many people use Mesh instead of Salesforce, Hubspot, and Pipedrive. Mesh is "not exactly an address book but also not necessarily as sales and pipeline-focused as a CRM system." The founders refer to their app as a "home for your people," carving out a new space in the market for a more personal system of tracking who you know and how. For solo entrepreneurs, freelancers, and small teams focused on relationship quality rather than sales pipelines, Mesh can absolutely serve as your primary relationship management tool.
Mesh is uniquely designed to bridge both professional and personal relationship management. Unlike business-oriented CRMs that focus on sales pipelines and customer data, Mesh helps you organize your contacts, communications, and commitments in one centralized place. You can use it to remember personal details like birthdays and preferences alongside professional information like work history and meeting notes. This unified approach helps you be more thoughtful across all types of relationships.
Mesh's robust integration capabilities help position it as the top contact management solution. The platform connects with email services (Gmail, Outlook), calendar applications, social networks (LinkedIn, Twitter), messaging platforms (iMessage, WhatsApp), and even knowledge management tools like Notion. Mesh has expanded its integrations catalog to include Zapier and Make.com support, allowing connections to thousands of other apps. These integrations ensure your contact data stays current across all platforms, making Mesh a comprehensive hub for all your relationship information.
Mesh's AI capabilities are at the forefront of personal CRM innovation. Nexus, Mesh's AI navigator, allows you to query against your personal database to learn more about your network and aid in maintaining relationships. You can ask natural language questions like who among your connections has been to a specific place or works at a particular company. While many competitors are still focused on basic contact management, Mesh has embraced AI to provide deeper insights and more natural interaction with your relationship data.
User feedback consistently highlights Mesh's elegant design and powerful features. Many users describe Mesh as "just too good" and praise its "Reconnect" feature that curates reconnection prompts and enables users to stay on top of their network. Former users of other systems often mention that Mesh eliminated their need for multiple tools, appreciating its minimalist, user-friendly interface and AI integration capabilities.
People also viewed
Related People